There is no fixed dollar income limit for Chapter 7. The test compares your household’s average income over the six full calendar months before you file against the median family income for your state and household size. Below that median, you pass and nothing further is required. Above it, a second calculation subtracts allowed expenses to see whether meaningful disposable income remains.
The detail that decides real cases is the six-month window, because it means the month you file changes the answer.
Part one: current monthly income
Add every dollar of household income received in the six full calendar months before the filing month, divide by six, multiply by twelve. That is your annualized figure, and it goes on Form B122A-1.
What counts is broader than “salary”:
- Wages, tips, bonuses, commissions, overtime
- Self-employment and business income
- Unemployment compensation
- Rental and investment income
- Pension and retirement income
- Regular contributions from anyone else to household expenses — including a non-filing spouse’s income and regular family support
What does not count: Social Security benefits are excluded from current monthly income, which is a significant carve-out. Certain payments to victims of war crimes and terrorism are also excluded.
Then compare against the median for your state and household size. Those figures are updated periodically and vary widely between states — get them from the current U.S. Trustee table, not from an article. A number published a year ago may no longer be the number your court applies.
Why the six-month window is the whole game
Because it is a rolling look at the past, not a measure of your situation now.
- You were laid off two months ago. Your six-month average still contains four months of full salary, so you may fail a test on income you no longer have. Waiting a month or two changes the average, and each month that passes drops a high month and adds a low one.
- A bonus landed in March. Filing in April includes it. Filing in October may not.
- You just started a much better job. The six-month average may still be low enough to pass — and waiting makes it worse, not better.
This is the single most valuable thing to understand about the means test, and it is why “I make too much for Chapter 7” is frequently wrong as a permanent statement. It is a statement about a specific filing date.
Part two: if you are above the median
Failing part one does not end it. Form B122A-2 subtracts allowed expenses from your income, using a mix of IRS national and local standards — food, clothing, housing, utilities, transportation, by county and household size — plus actual amounts for certain categories: taxes, mandatory payroll deductions, insurance, childcare, court-ordered payments, secured debt payments on property you are keeping, and priority debt like support arrears and recent taxes.
If what remains is below the statutory thresholds, the presumption of abuse does not arise and you can proceed with Chapter 7 despite being above the median. A meaningful number of above-median filers pass here, particularly those with a mortgage, a car payment and dependents.
Four ways people qualify who assumed they could not
- Timing the filing so the six-month window reflects reduced income.
- Passing the expense calculation in part two — high secured payments and dependents do most of the work.
- Debt that is primarily non-consumer. If more than half your debt is business debt rather than consumer debt, the means test does not apply at all. This catches people who guaranteed a failed business.
- The service member and veteran exemptions. Disabled veterans whose debt was incurred primarily during active duty or homeland defense activity, and reservists and National Guard members called to active duty for a qualifying period, are excluded from the test under §707(b)(2)(D).
What happens if you genuinely fail
The case does not simply get rejected — you are routed toward Chapter 13, where you repay a court-approved amount over three or five years and receive a discharge at completion. Whether that is bad news depends on the rest of your picture: if you have a mortgage in arrears or non-exempt equity, Chapter 13 may have been the better chapter regardless. See what happens if you are routed to Chapter 13.
The mistake to avoid: manufacturing a pass
Do not reduce income, delay income, or shuffle assets in order to pass. Payments to relatives, sudden transfers and unusual timing are exactly what trustees look at, and the consequences range from a denied discharge to a fraud referral. Filing at a moment when your income is genuinely lower is legitimate planning. Making your income look lower is not, and the line between the two is a question for an attorney, not for a spreadsheet.
The same income passes in 28 jurisdictions and fails in 27
This article has so far refused to print median figures, on the reasoning that a stale one is worse than none. That objection has a condition attached, and the condition is a date. So here they are with the date stamped on them: the table below is the one the U.S. Trustee Program applies to cases filed on or after the fifteenth of July, 2026, and we read it on September 2, 2026. When the next table takes effect, the counts on this page expire with it.
Take a one-person household on seventy thousand dollars of annualised income. In 28 of the 55 jurisdictions the Trustee Program publishes, that is below the median and part one of the test is passed. In the other 27 it is above, and the second form has to be filled in. 50.9% of the table sits on the passing side of the line and the rest on the other: the same dollar figure, the same household, opposite outcomes, decided by which federal district the case is filed in.
Move the income and the cliff appears. At sixty thousand dollars the same household is below the median in 48 of the 55. At eighty thousand, in eleven. At ninety thousand, in none of them. So the whole range in which geography decides the answer sits between sixty and ninety thousand dollars for a household of one. Below it, almost everyone passes part one; above it, nobody does.
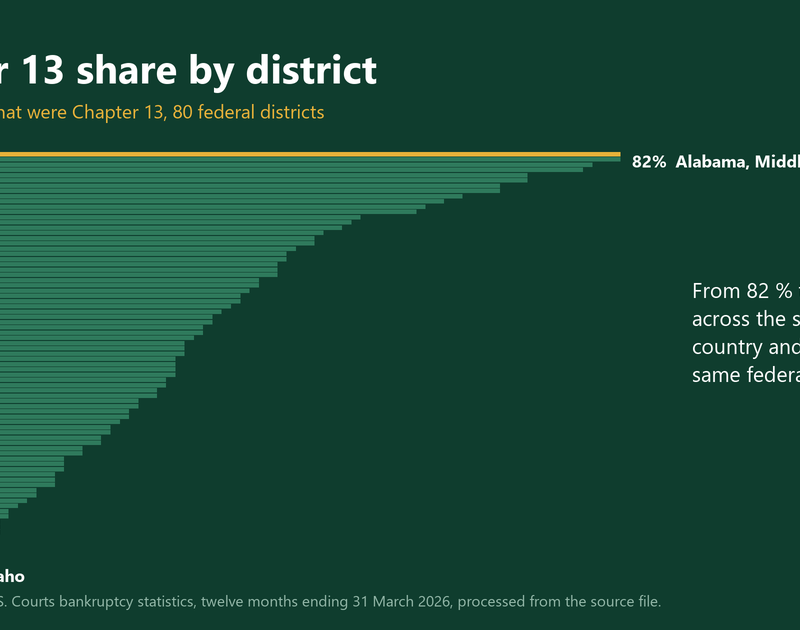
The chart shows why 28 against 27 is such a fine split. The ten jurisdictions nearest the seventy-thousand-dollar line are separated by a few thousand dollars in total, so the median is not a wall that some states build high and others low — around the middle of the distribution it is a crowd. A raise, a change of household size or a move across a state border moves you through several of these at once. If your district is one of them, the answer to do I make too much for Chapter 7 is genuinely close, and being routed to a court-supervised repayment plan instead is not a foregone conclusion — nor is it necessarily the worse outcome, since what a discharge clears is the same list in both chapters.
| Annualised income | Below the median (part one passed) | Above the median | Share below |
|---|---|---|---|
| $40,000 | 53 of 55 | 2 | 96.4% |
| $50,000 | 52 of 55 | 3 | 94.5% |
| $60,000 | 48 of 55 | 7 | 87.3% |
| $70,000 | 28 of 55 | 27 | 50.9% |
| $80,000 | 11 of 55 | 44 | 20.0% |
| $90,000 | 0 of 55 | 55 | 0.0% |
| $100,000 | 0 of 55 | 55 | 0.0% |
| $120,000 | 0 of 55 | 55 | 0.0% |
A threshold that runs from thirty thousand to eighty-nine thousand
The spread across jurisdictions is the reason no article can print one income limit. For a one-person household the lowest published threshold is $30,665, in Puerto Rico. The highest is $88,585, in Washington. That is 2.89 times as much, a difference of $57,920, and the middle of the fifty-five is $71,168 — which is why seventy thousand dollars splits the table almost exactly in half. Household size widens it further: for a household of two the ratio is 5.26, from the same floor up to $161,397 in the District of Columbia.
Three cautions come with these numbers and each one changes what you can do with them. First, the threshold is only the first gate. Being above the median does not close Chapter 7; it moves the case to the expense calculation on the second form, which filers with a mortgage, a car payment and dependents pass regularly. Nothing in this table predicts that second step, and the exemptions that apply to your case are a separate matter again — see how exemptions vary by state.
Second, the income being compared is not your salary. The test totals the household’s income across the six full calendar months before the filing month and doubles it. A year of earnings is not the input, which is why this grid is an order-of-magnitude guide and not a calculation: someone laid off in month five has a very different annualised figure from their W-2. That is the same mechanism the section above describes, and it is what makes the filing date part of the arithmetic.
Third, a new table is not always a new number. We compared the table now in force against the one it replaced, which covered cases filed from the first of April to the fourteenth of July. The medians are identical in all 55 jurisdictions. The tables are separate documents with separate effective dates, and the underlying medians only move when the Census data behind them moves — so citing the newest table does not by itself mean citing a changed figure, and an article quoting last quarter’s table may still have had the right number. What it would not have had is the certainty. Before you rely on any of this, open the current table, and if you are filing without counsel read what filing without a lawyer involves and what the filing actually costs first.
| Source | Executive Office for United States Trustees, U.S. Department of Justice, median family income table used for the Chapter 7 means test (Forms 122A-1 and 122C-1), built from Census Bureau median family income data |
|---|---|
| What we asked it | We took the whole table in force for cases filed on or after July 15, 2026 — 55 jurisdictions by household size — and counted, for each of eight annual income levels, how many jurisdictions publish a median above that level. We then read the highest and lowest value of each household-size column and compared the whole table against the one previously in force, cell by cell. |
| Data as of | Median family income table for cases filed on or after July 15, 2026 |
| Retrieved | September 2, 2026 |
| Assumptions | An income is treated as passing part one when it is strictly below the published median for that jurisdiction and household size; jurisdictions are counted unweighted: Puerto Rico and Guam each count once, as does California, so the counts describe the table and not the population; the annual figures in the grid are treated as already annualised current monthly income, which is not the same thing as a calendar year of earnings |
| How to repeat it | Open the U.S. Trustee Program means testing page, choose the table for cases filed on or after July 15, 2026, and count the jurisdictions whose one-person median exceeds seventy thousand dollars. The count is 28 of 55; every other figure here is the same count at a different income or the maximum and minimum of a column. |
| Household size | Lowest threshold | Highest threshold | Difference | Ratio | Middle of the 55 |
|---|---|---|---|---|---|
| One person | Puerto Rico, $30,665 | Washington, $88,585 | $57,920 | 2.89x | $71,168 |
| 2 people | Puerto Rico, $30,665 | District of Columbia, $161,397 | $130,732 | 5.26x | $89,027 |
| 3 people | Puerto Rico, $40,976 | District of Columbia, $161,397 | $120,421 | 3.94x | $103,449 |
| 4 people | Puerto Rico, $50,543 | Massachusetts, $178,524 | $127,981 | 3.53x | $125,074 |
What this does not say.
- The threshold is the first gate and not the test. Above the median, the case proceeds to the expense calculation on Form B122A-2, and this table says nothing about whether that second step is passed.
- The income compared is not annual income. The means test uses the household’s total income over the six full calendar months before filing, doubled, so this grid is an order-of-magnitude guide rather than a calculation of anyone’s case.
- These counts are of jurisdictions, not of people. Every jurisdiction counts once whatever its population, so the share below the median describes the table and not the country.
- The figures expire. They carry the effective date of the table for cases filed on or after the fifteenth of July, 2026; a later table supersedes them, and we have shown that a new table does not always change the medians but cannot promise the next one will not.
- What counts as household income is a classification question, not an arithmetic one. Social Security is excluded, a non-filing spouse’s contribution is generally included, and the whole category of non-consumer debt cases sits outside the test. None of that is in this table.
Frequently asked questions
What is the income limit for Chapter 7? There is no fixed dollar limit. You are compared against the median family income for your state and household size. For scale, on the table in force for cases filed on or after July 15, 2026, a one-person household on seventy thousand dollars is below the median in 28 of 55 jurisdictions and above it in 27. Get the current figure from the U.S. Trustee table, not from an article.
Which state has the lowest Chapter 7 income limit? Of the 55 jurisdictions in the current table, Puerto Rico publishes the lowest one-person threshold at $30,665 and Washington the highest at $88,585. That is 2.89 times as much for the same household size, which is why no single national income limit exists or could.
Can I file Chapter 7 if I make too much money? Often, yes. Above-median filers go through an expense calculation on the second form, and those with mortgages, car payments, dependents or high mandatory deductions frequently pass it. Separately, filers whose debt is mostly non-consumer, and certain veterans and reservists, are exempt from the test entirely.
Does Social Security count in the means test? No. Social Security benefits are excluded from current monthly income. They may still appear elsewhere in your schedules and in a Chapter 13 budget analysis, so excluded from the test is not the same as invisible to the court.
If I fail the means test, can I try again later? Yes. The calculation is tied to the six full calendar months before filing, so a later filing uses a different window and can produce a different answer. This is a routine reason to wait, and it is why failing is a statement about a filing date rather than about you.
This article explains the means test in general terms. It is not legal advice. The median income figures below are the table in force for cases filed on or after 15 July 2026, and they are dated for that reason: they are revised periodically and an out-of-date number would be worse than no number. Check the current U.S. Trustee table before relying on one, and confirm your calculation with a bankruptcy attorney in your district.
Sources
- DOJ U.S. Trustee Program — Means Testing Information, median family income tables and national/local expense standards
- 11 U.S.C. §707(b) — abuse and the presumption
- Official Form B122A-1 — Chapter 7 Statement of Your Current Monthly Income
- Official Form B122A-2 — Chapter 7 Means Test Calculation
- U.S. Trustee Program, U.S. Department of Justice — Median Family Income Based on State/Territory and Family Size, for cases filed on or after July 15, 2026 (accessed 2026-09-02)
- U.S. Trustee Program — the table it replaced, for cases filed between April 1, 2026 and July 14, 2026, inclusive (accessed 2026-09-02)
Information, not advice. How we calculate, source and review this — and what we do not do — is set out on our methods and sourcing page.