Writes and edits PayoffPath. Not a lawyer, not a credit counsellor and not a financial adviser: the work here is reading the primary sources - the U.S. Courts statistics tables and the official bankruptcy forms, the CFPB, the FTC, the eCFR and the Federal Reserve - checking the date on every figure, and setting it out in plain English. There is no professional review behind these articles, and the site says so rather than implying a credential it does not have: where a decision turns on your own circumstances, the page points you to the court, the agency or the attorney that can answer it.
At the measured 22.15% APR: $500 clears $10,000 in 26 months, $200 in 141, and anything at or under $184.58 never. The headline 27 is at a stated 24.99%.
The stack above is measured against the balance. Paying the same balance at 22.15 percent adds 7,553 dollars over three years, and a fee inside the documented band eats every…
Three tests answer it, and none of them is a national average. Plus what the Federal Reserve's 1.35 trillion revolving credit total can and cannot tell you.
Modification comes first; the hardship discharge is what becomes reachable when it is not possible. Plus the federal counts: 214,153 consumer plans started in a year, and why no completion…
Reading Regulation F on the thirty-day validation period. Plus how often the notice itself is the complaint: 54,617 of 324,326 federal collection complaints.
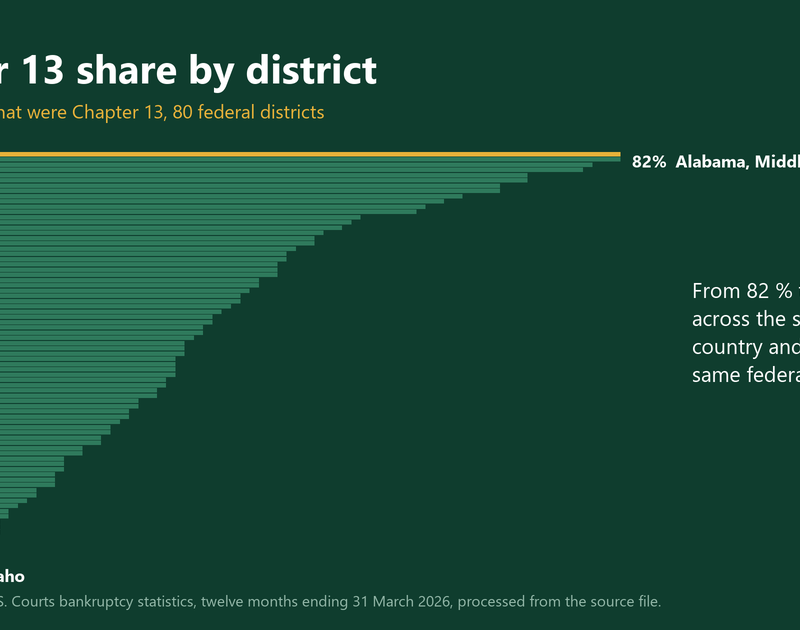
Chapter 13's share of consumer bankruptcies by federal district, rebuilt from the June 2026 court release: 36.9% nationally, 82.1% in one district and 8.1% in another, plus filings per head…
Five different things sold under one phrase. Plus the federal record: money comes back in 14.35% of card complaints and 0.13% of collection complaints.
Chapter 7 is faster and cheaper; Chapter 13 does what 7 cannot. Plus the federal filing data: 36.9% of consumer cases are Chapter 13 nationally, 82.1% in one district and…
We use cookies to run this site, to measure which articles are read, and — where you allow it — to show advertising. You can accept, reject, or read exactly what each one does.